An “extended auto warranty” can be worth buying when it covers repairs you could not comfortably pay for and the full price fits your budget. Most plans sold after the factory warranty are vehicle service contracts. Read the agreement to find out what the advertised “protection” includes.
The car's age and mileage are only part of the decision. Compare the price, covered systems and claim limits with the repairs you are concerned about.
Know which product you are buying
A manufacturer warranty comes with the vehicle and covers certain defects for a stated time or mileage. Bought separately, a service contract may cover mechanical or electrical failures after the factory coverage ends, although the Consumer Financial Protection Bureau says these products often exclude routine maintenance and normal wear.
Check for overlapping coverage before calculating repair costs. If the factory powertrain warranty still has two years left, you could pay for a new plan that duplicates protection during part of its term.
Get the sample contract before paying, then identify the company authorizing claims and the party legally responsible for benefits. The Federal Trade Commission recommends checking the provider’s reputation and state complaint history. A generous parts list has limited value if the company behind it cannot handle a claim.
Calculate the full contract cost
Ignore the monthly payment at first. Use the complete contract price, then add financing charges and the deductible you would owe on a claim. A $3,000 plan rolled into a five-year loan at a hypothetical 8% rate costs about $3,650 by the final payment. That extra $650 is roughly six $100 deductibles paid before the vehicle needs a single repair.
Now test an actual outcome. Suppose the car later needs a $4,000 transmission repair, the failure is covered and the deductible is $100. The contract pays $3,900. Against the financed cost above, the owner comes out only about $250 ahead. An uncovered diagnostic fee would reduce that saving.
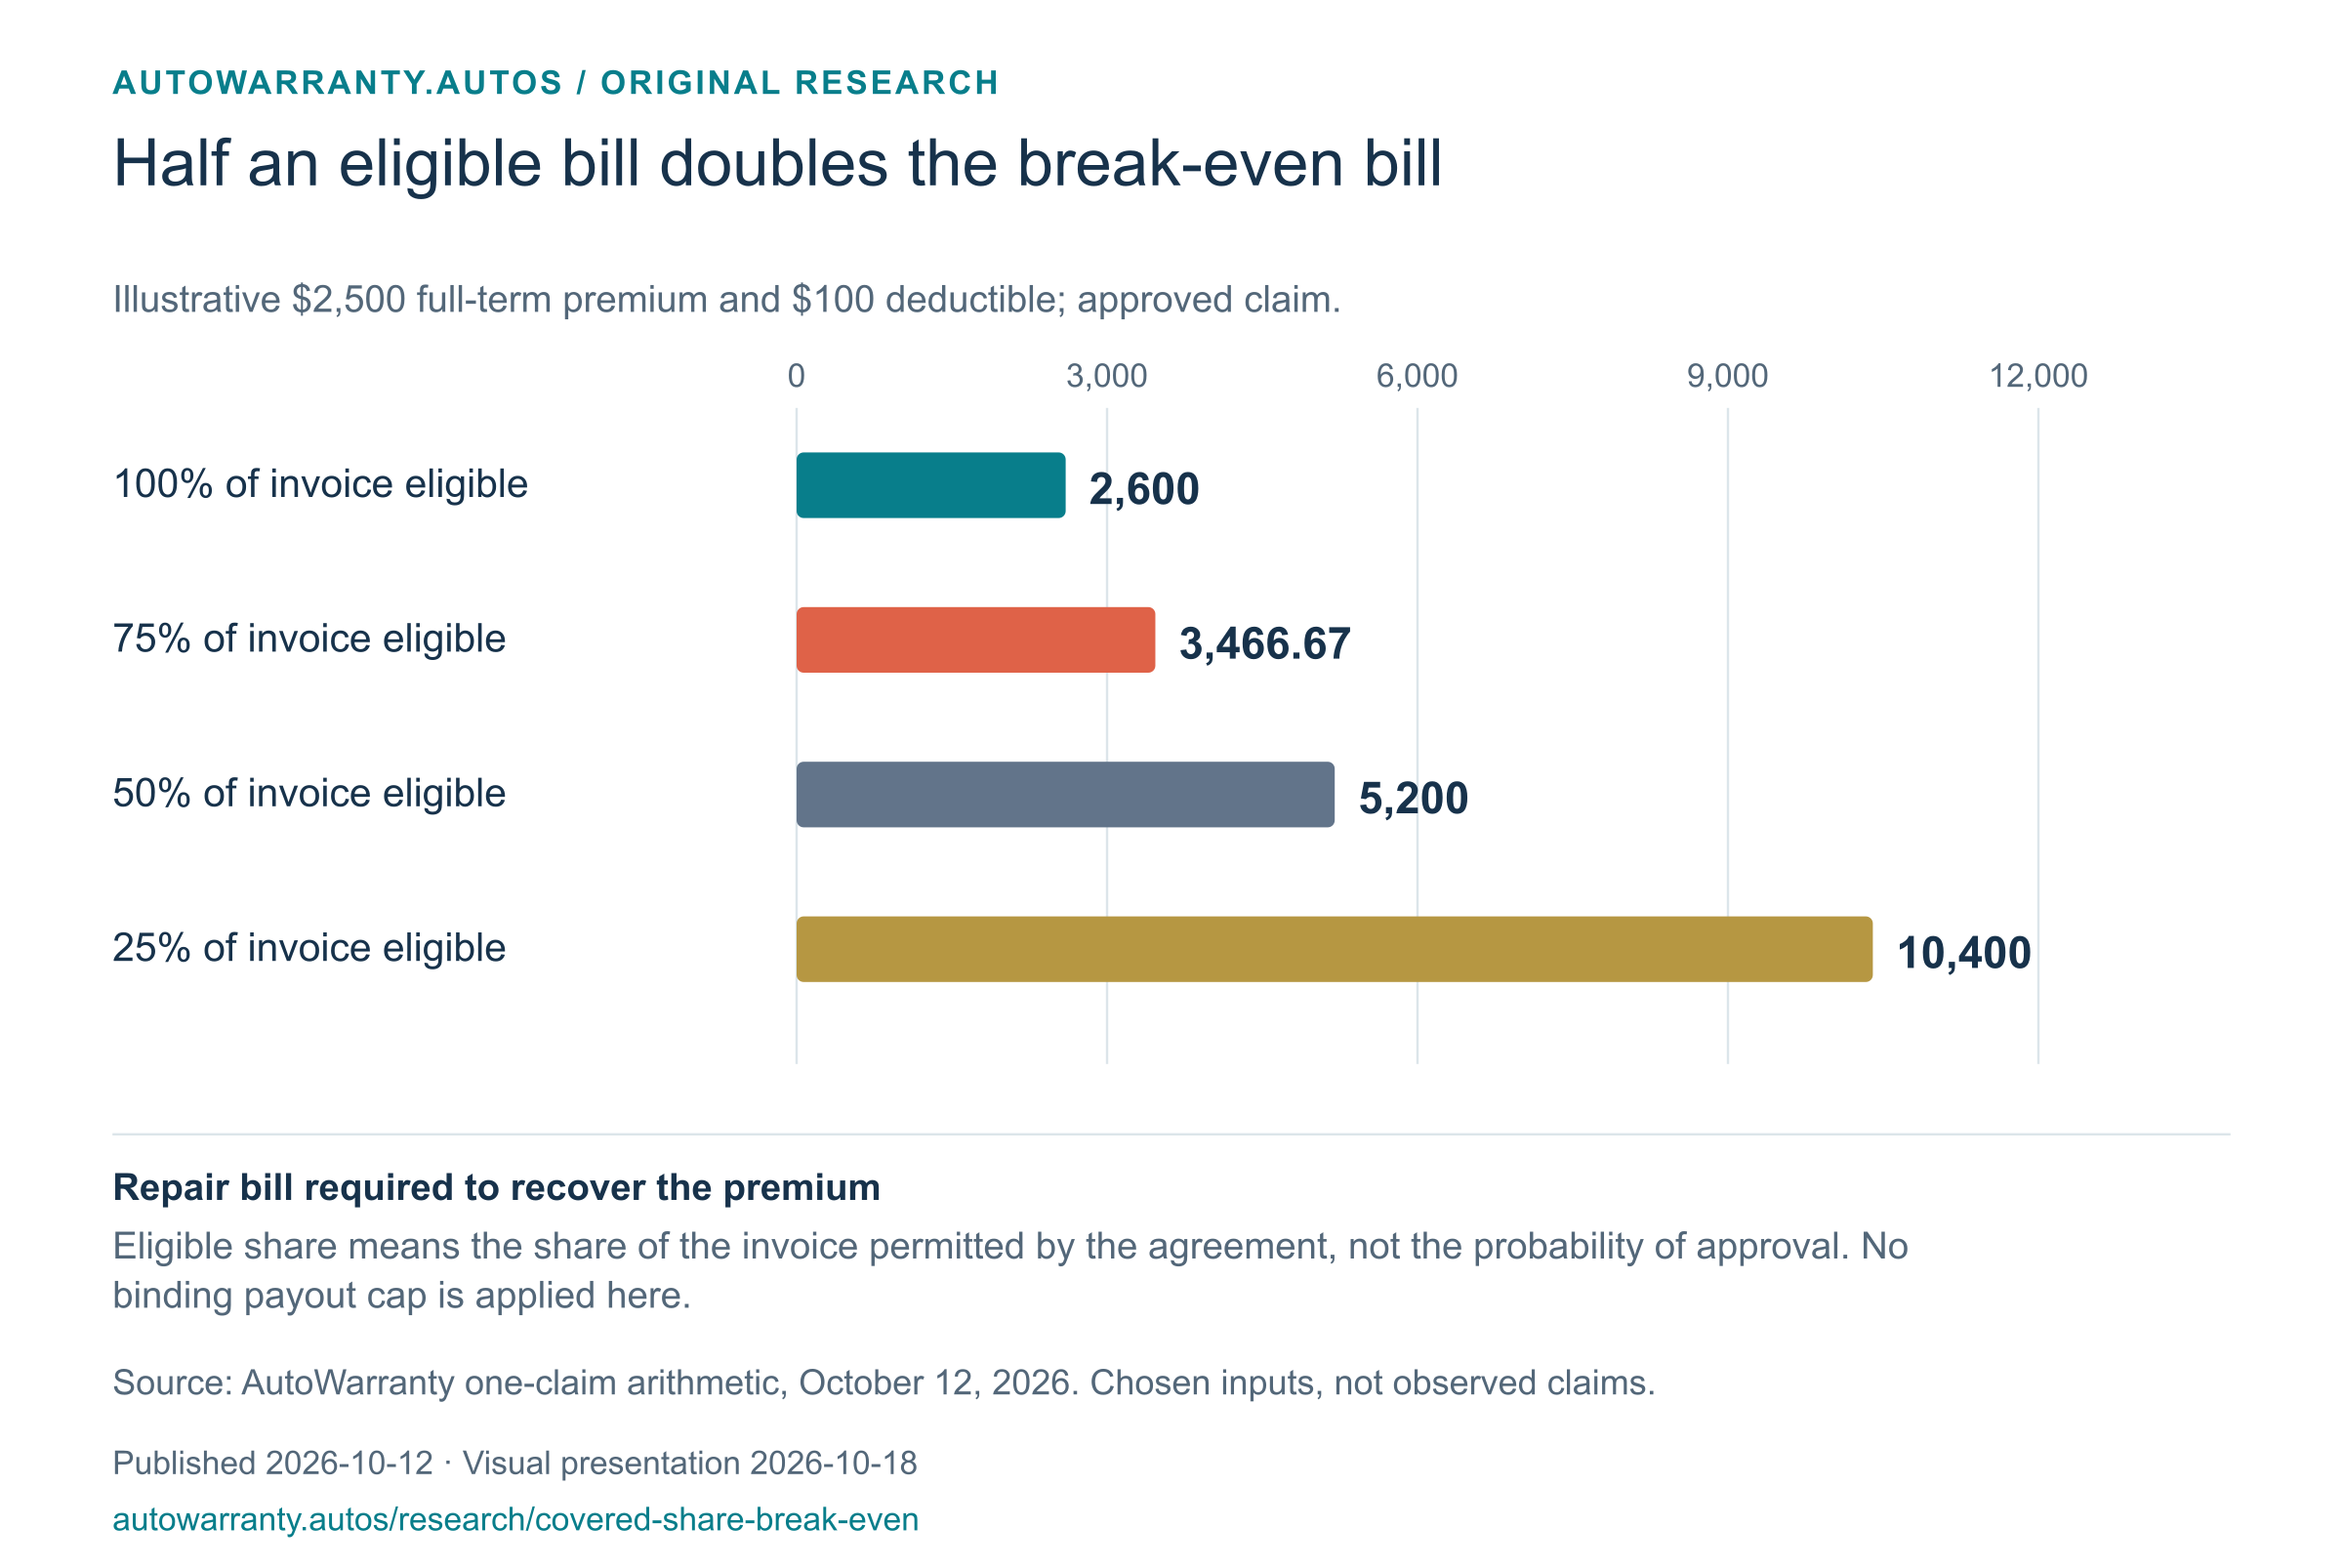
With no covered repair, the premium is an added cost. Two eligible claims could make the plan more valuable. Because we cannot predict which repairs will occur, compare several outcomes using the contract's actual coverage and calculate how much it would need to pay to break even.
Read exclusions as well as covered parts
An exclusionary contract generally covers parts unless it names them as exclusions. A named-component contract works in reverse: if the part is missing from the covered list, assume you are paying the bill. Neither label tells you whether the plan is good.
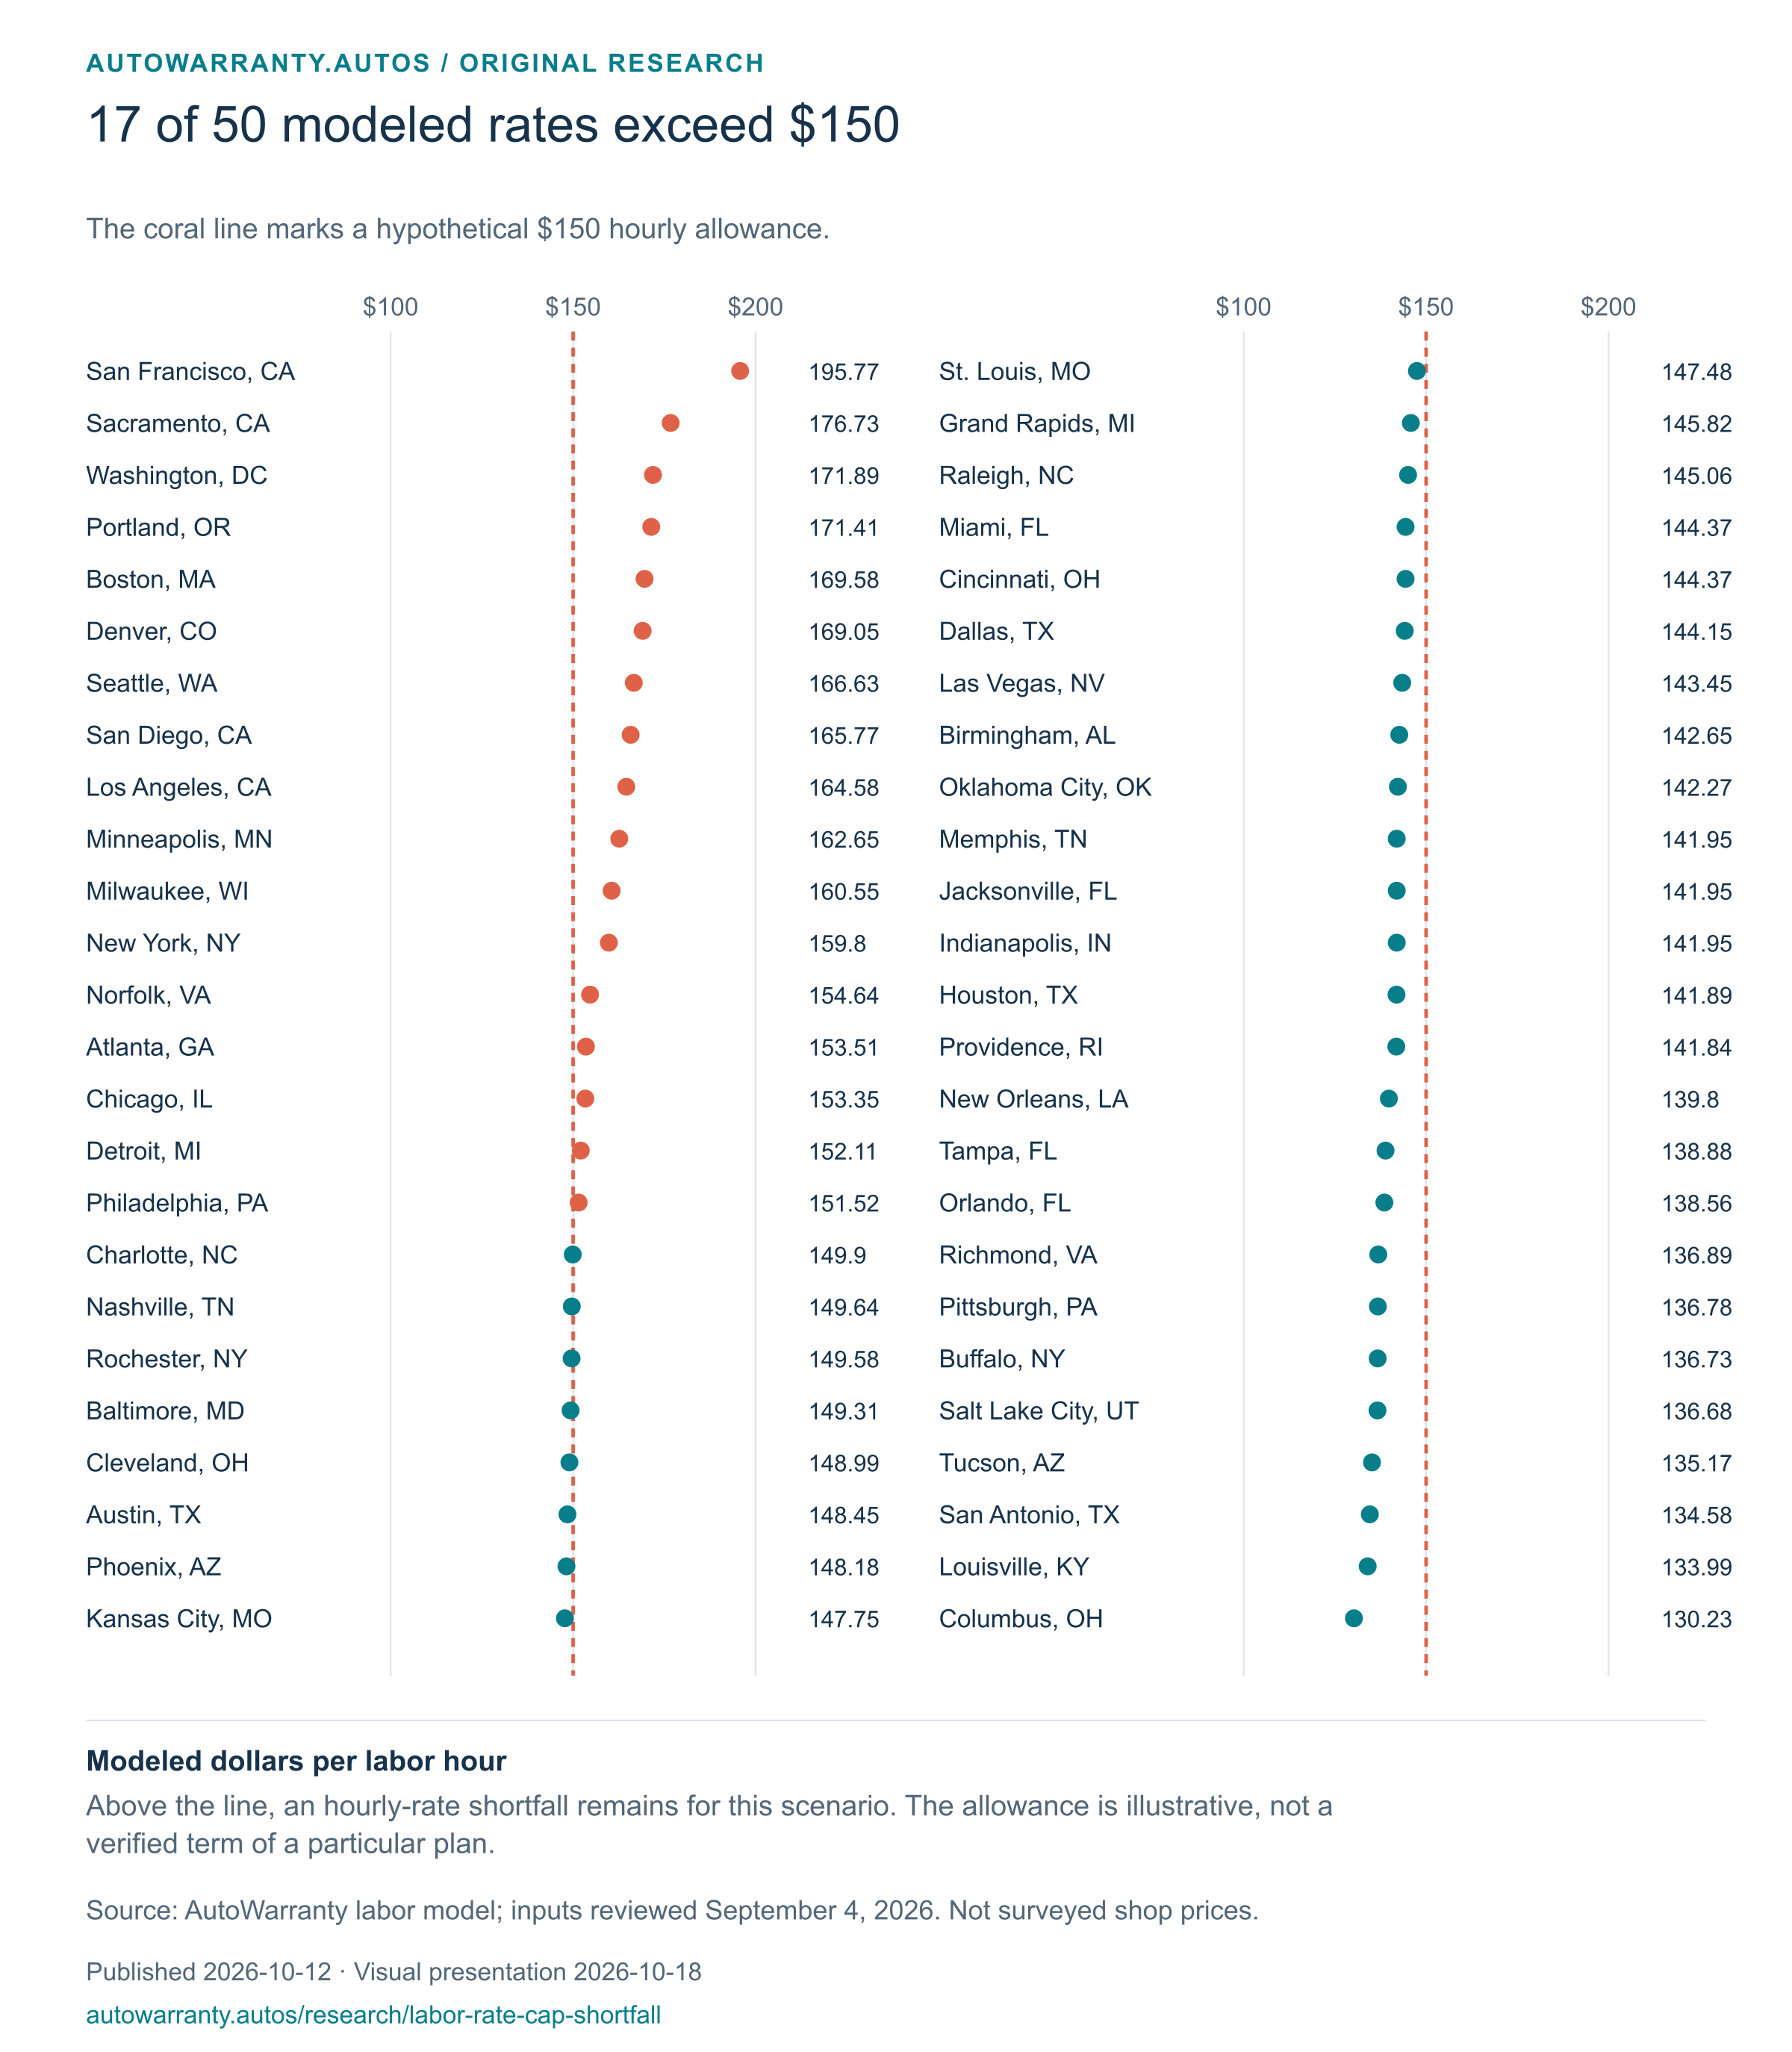
Look closely at pre-existing-condition language and maintenance-record requirements. Some contracts require approval before a shop tears down the vehicle. Labor-rate limits can leave part of the invoice with you, while towing benefits may have a separate cap. The FTC warns that a difficult claims process reduces the value of coverage even when the repair appears eligible.
Wear items are another source of disappointment. Brake pads and tires are usually maintenance costs, not mechanical-breakdown claims. If most of the bills you expect are for maintenance, an extended auto warranty is probably a poor fit.
An older car is not automatically a better candidate
The average light vehicle in the United States reached 12.8 years old in 2025, according to S&P Global Mobility. That was two months older than the prior year, so American drivers are keeping a lot of machinery on the road well beyond its factory coverage.
Age alone tells us little about a particular offer. Coverage for an eight-year-old model with costly electronics may be worth considering when local labor is expensive and the contract covers those systems. A car of the same age with lower repair costs may not justify an expensive plan.
Mileage changes eligibility and price, while your cash reserve changes the value of certainty. A driver who can comfortably absorb a $4,000 bill can self-fund the risk and keep any unused money. Someone who would need high-interest debt for the same repair may reasonably pay more for predictable costs, even if the contract is unlikely to save money overall.
Our buying rule
Consider buying only if a plausible major covered repair could repay the full plan cost with a worthwhile saving. Also check that the expensive systems you want protected are covered and that no exclusion rules out the failures you are concerned about.
Then compare competing plans using the same vehicle, deductible and mileage. A lower price may simply reflect a shorter list of covered parts.
If the numbers are close, consider how you would pay for a major repair. Set money aside when you can absorb an unexpected bill and the contract is unlikely to repay its cost. Compare service contracts when a covered failure would strain the household budget, and read the agreement before buying.
Primary research
Sources reviewed
- Extended Warranties and Service ContractsFederal Trade Commission
- Manufacturer Warranties vs. Extended Vehicle WarrantiesConsumer Financial Protection Bureau
- What Is Included in a Monthly Auto Loan Payment?Consumer Financial Protection Bureau
- Auto Repair BasicsFederal Trade Commission
- U.S. Vehicle Age Rises to 12.8 Years in 2025S&P Global Mobility
Financial examples are hypothetical unless identified as published data. Coverage and contract rules vary by provider, vehicle and state.