How the two comparisons work
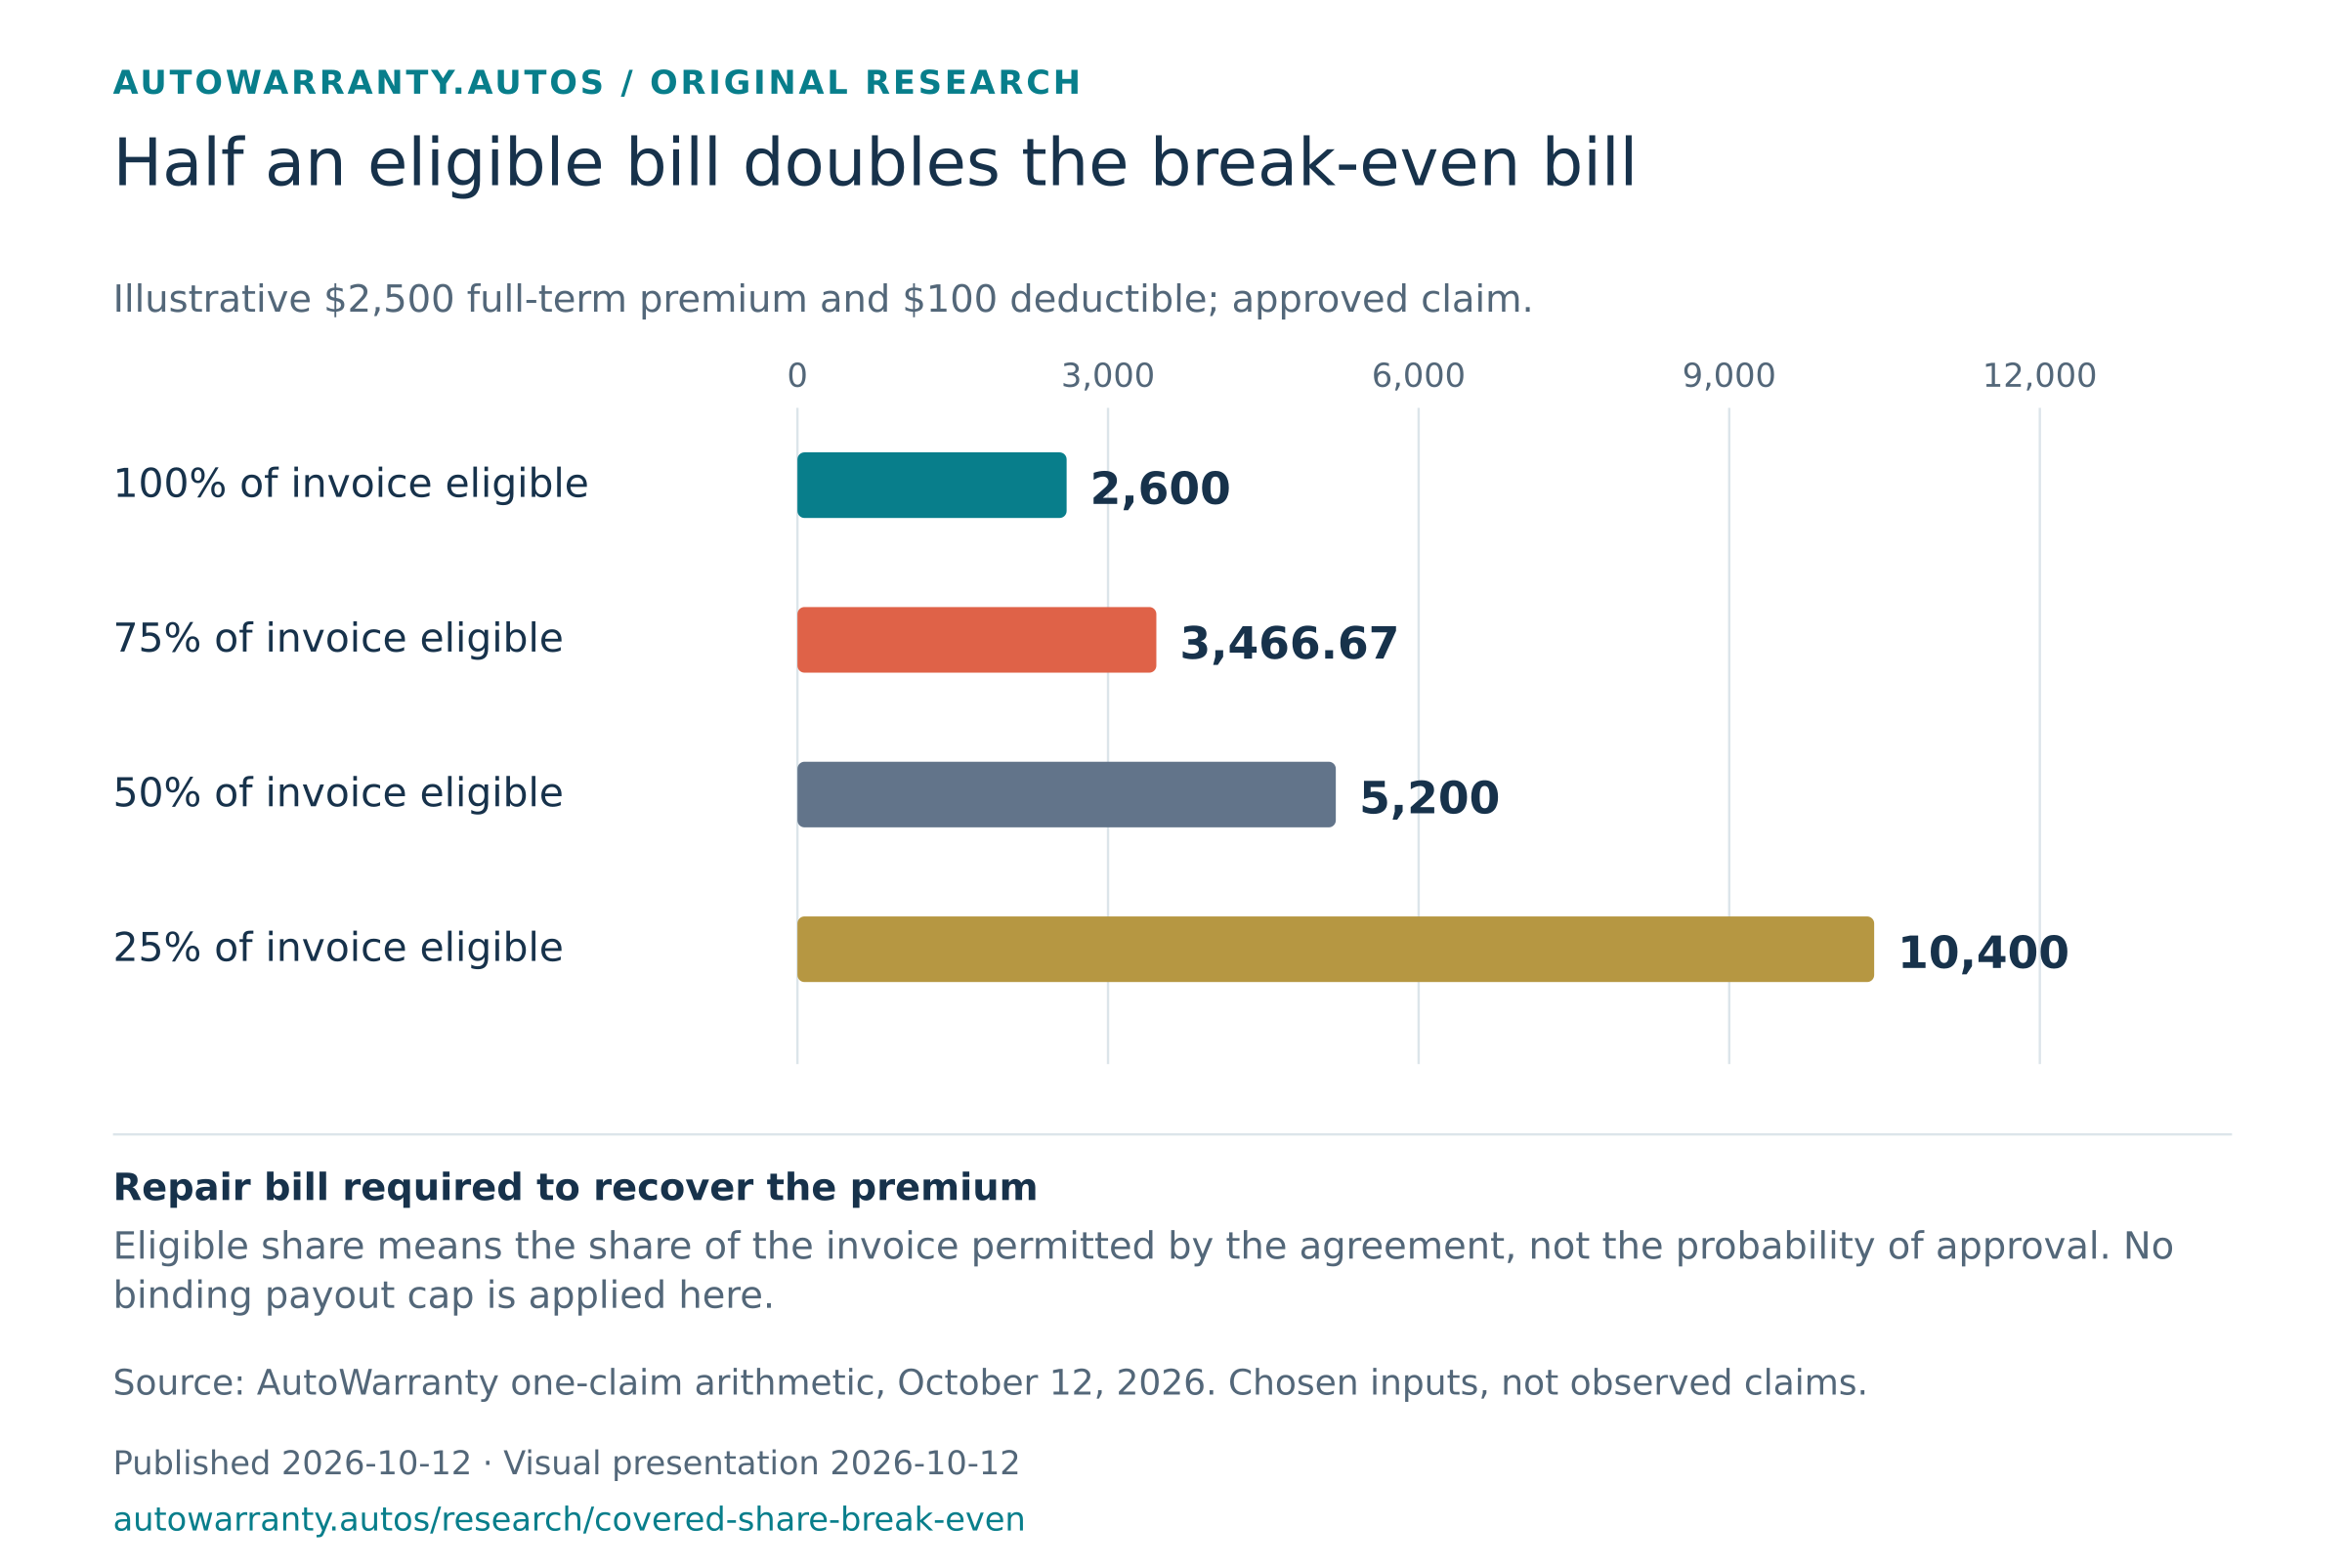
The single-repair check compares one hypothetical bill with the full plan premium, deductible, eligible share and payout cap. At break-even, savings are zero. No repair or a denied claim leaves the full premium as an added cost. That bill is not added to the separate average-based budget below.
We multiply the available annual repair and maintenance average by your selected years. Where a model average is unavailable, the result identifies the broader brand or all-vehicle reference. We do not predict an individual car's failures.
The premium is a published example scaled to your time frame, not an offer for your vehicle. Replace it with the full price of a quote covering that period. A five-year budget does not establish that a five-year plan is available.
Potential savings subtract the premium from assumed reimbursement. Maintenance, excluded work and deductibles stay in your budget. Change the coverage and claims assumptions, including zero claims, to see how much the answer depends on them.
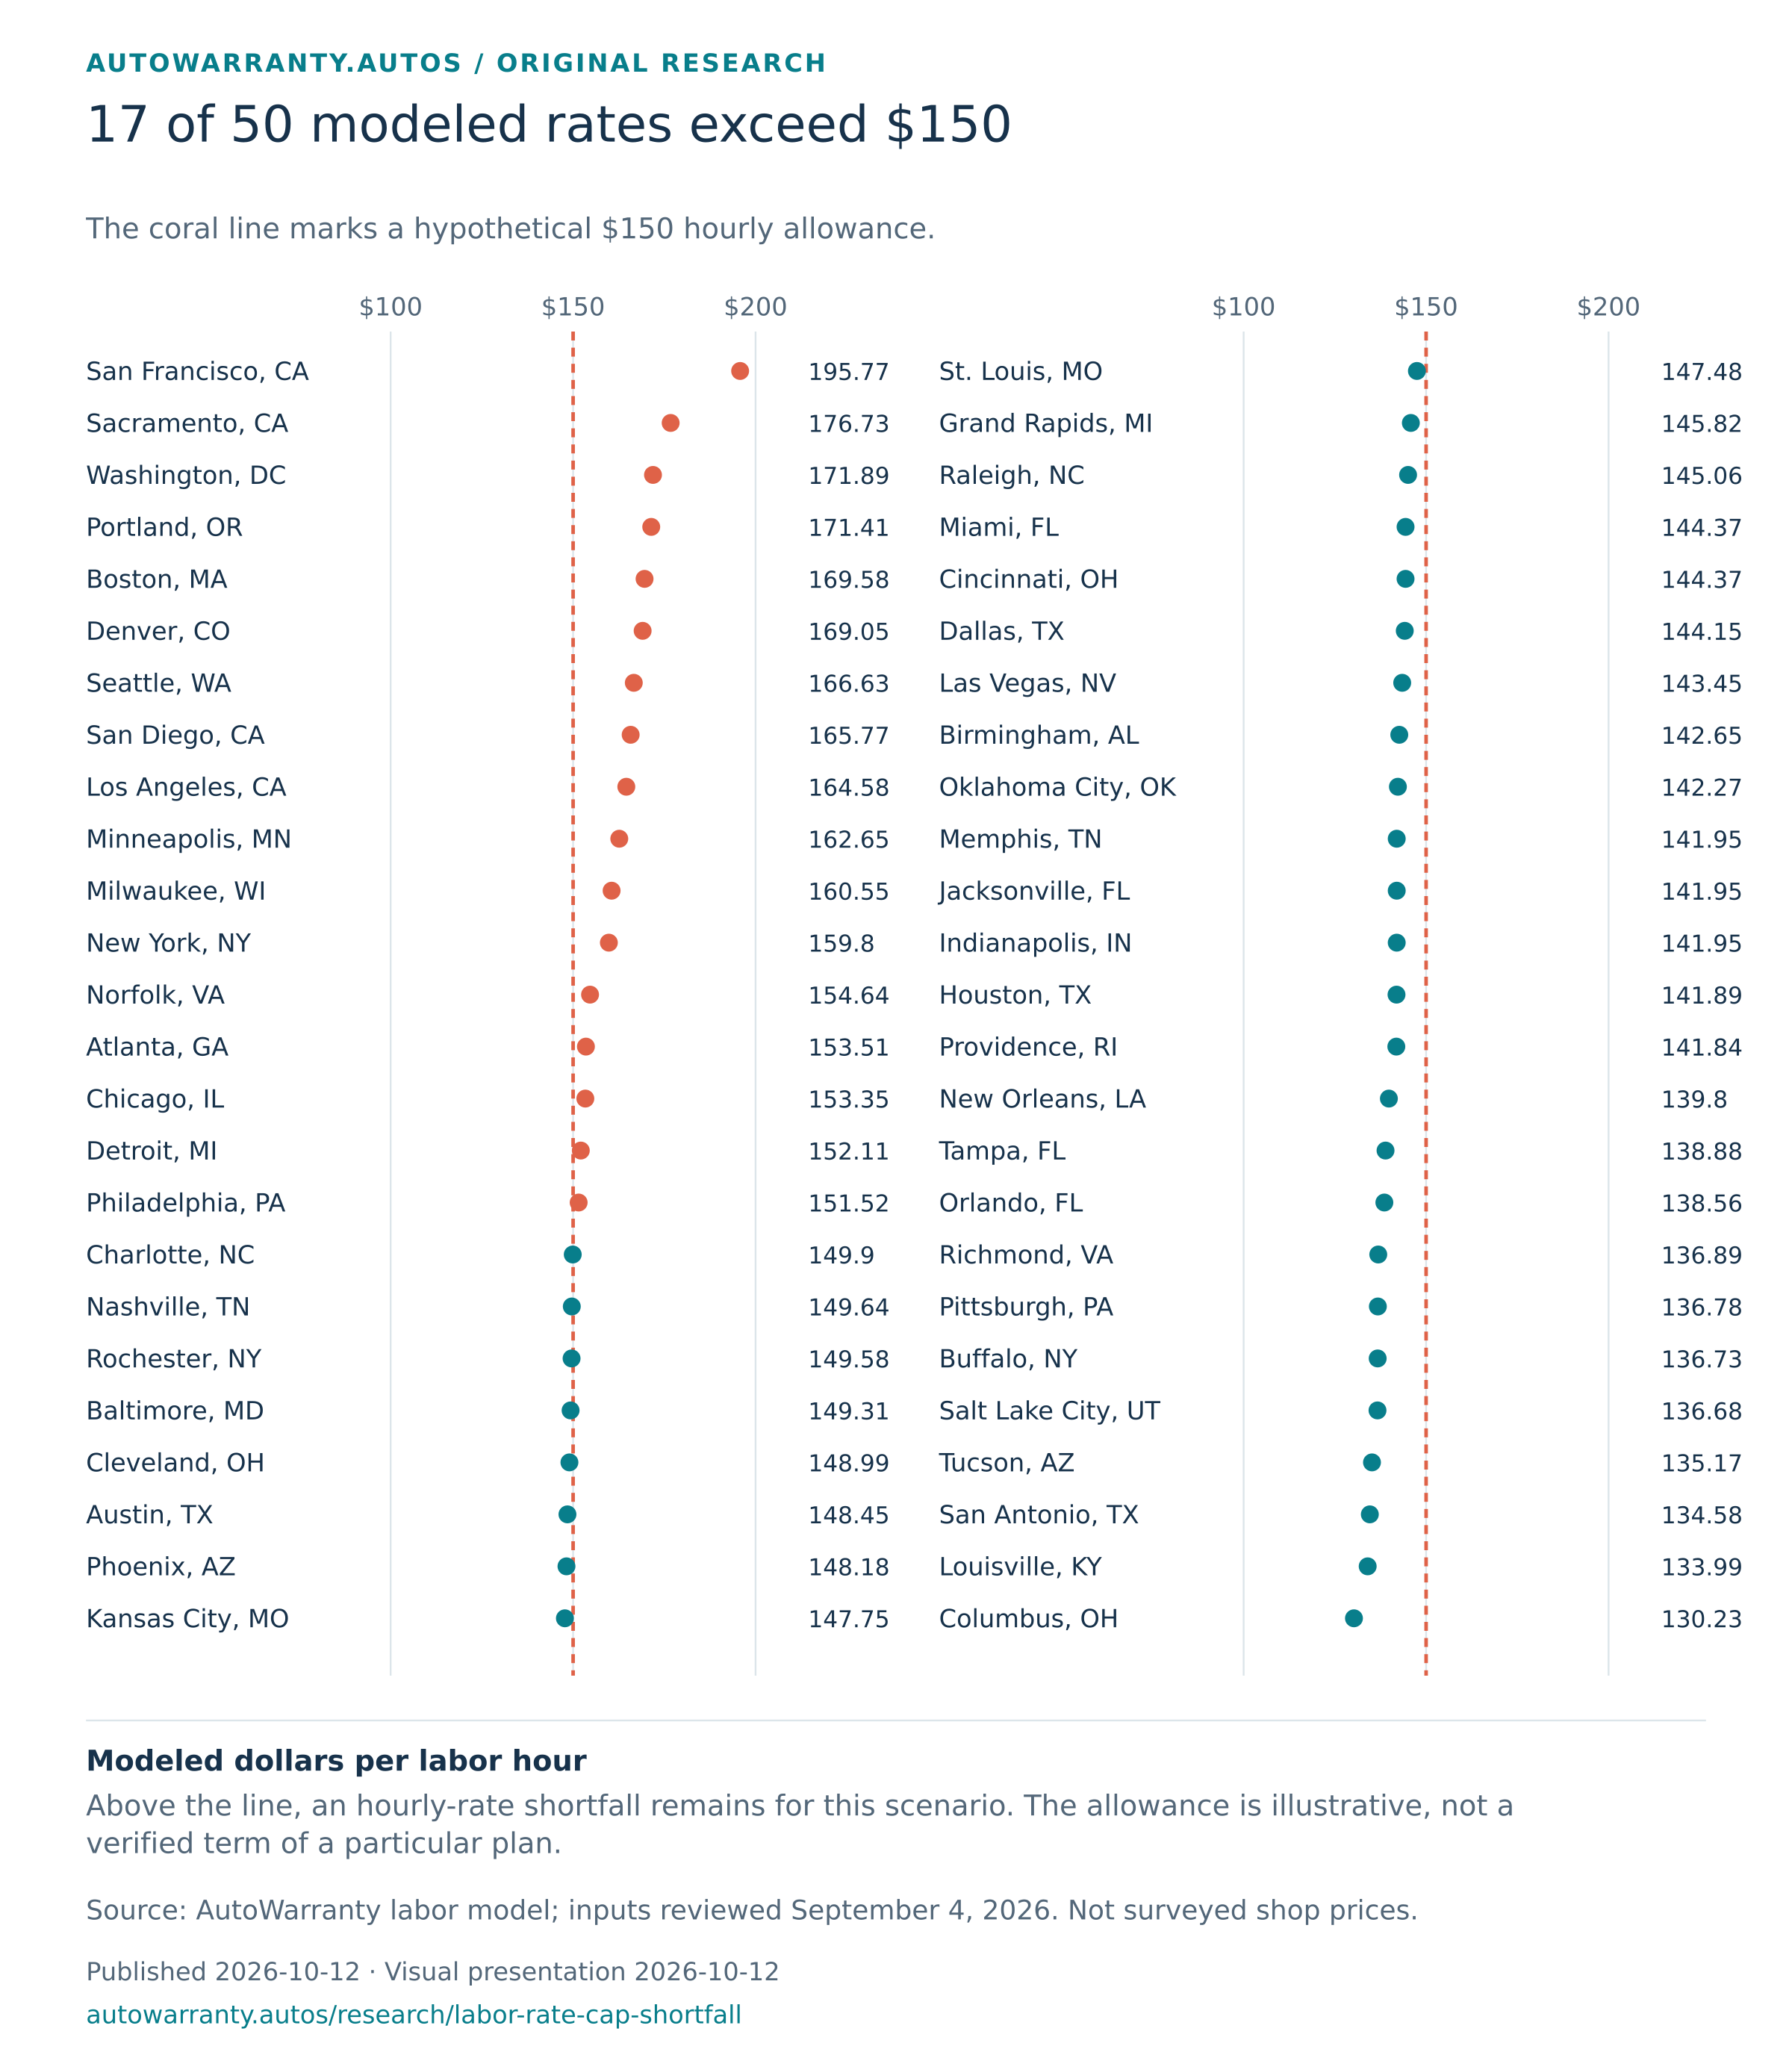
Our repair labor cost study shows how the same modeled job changes with location. Our NHTSA complaint audit explains why complaint counts cannot supply your car's failure odds.
Read our full methodology →