How we choose a best fit
We compare published eligibility rules, coverage descriptions and available sample contracts. We have not purchased these plans, submitted test claims or collected identical vehicle-specific quotes. These are editorial recommendations for a particular need, not a ranking of claims performance or the entire market.
First rule out plans that will not accept the car or cover the concern. Then compare the same term, mileage allowance, deductible and total price. A lower monthly payment does not win if it buys materially less coverage. Manufacturer programs and a repair savings account remain valid alternatives to the providers on Chaiz.
Older vehicles: the broadest eligibility is not the broadest coverage
Omega Powertrain accepts vehicles under 250,000 miles, up to the current model year plus 15 prior years. Broader tiers have tighter limits. Express Enhanced Powertrain considers vehicles up to 20 years and 150,000 miles at sale; Endurance also advertises coverage for vehicles up to 20 years. The quote determines the accepted tier.
For a low-value vehicle, also ask what the contract could pay in total. A benefits ceiling tied to the vehicle's value can leave much less usable protection than a long covered-parts list suggests. Read the high-mileage analysis before comparing payments.
Broad protection
Endurance Supreme and Omega Exclusionary are sensible agreements to investigate when the concern extends beyond the engine and transmission. Exclusionary means coverage is defined partly by what the contract leaves out. It does not mean every bill is paid or that the plan duplicates a factory warranty.
Express Premium switches to Enhanced Powertrain coverage at 150,000 odometer miles; Express Exclusionary Deluxe switches at 130,000. Express publishes five plans, while Chaiz lists Enhanced Powertrain and Stated. A plan that starts with broad coverage may become narrower during ownership.
When a repair fund is the better starting point
Keeping the money can suit a driver who can absorb a major bill, plans to sell soon, or finds that the available agreements exclude the main concern. Unused savings stay yours. A warranty premium buys protection during its term; it is not a savings balance.
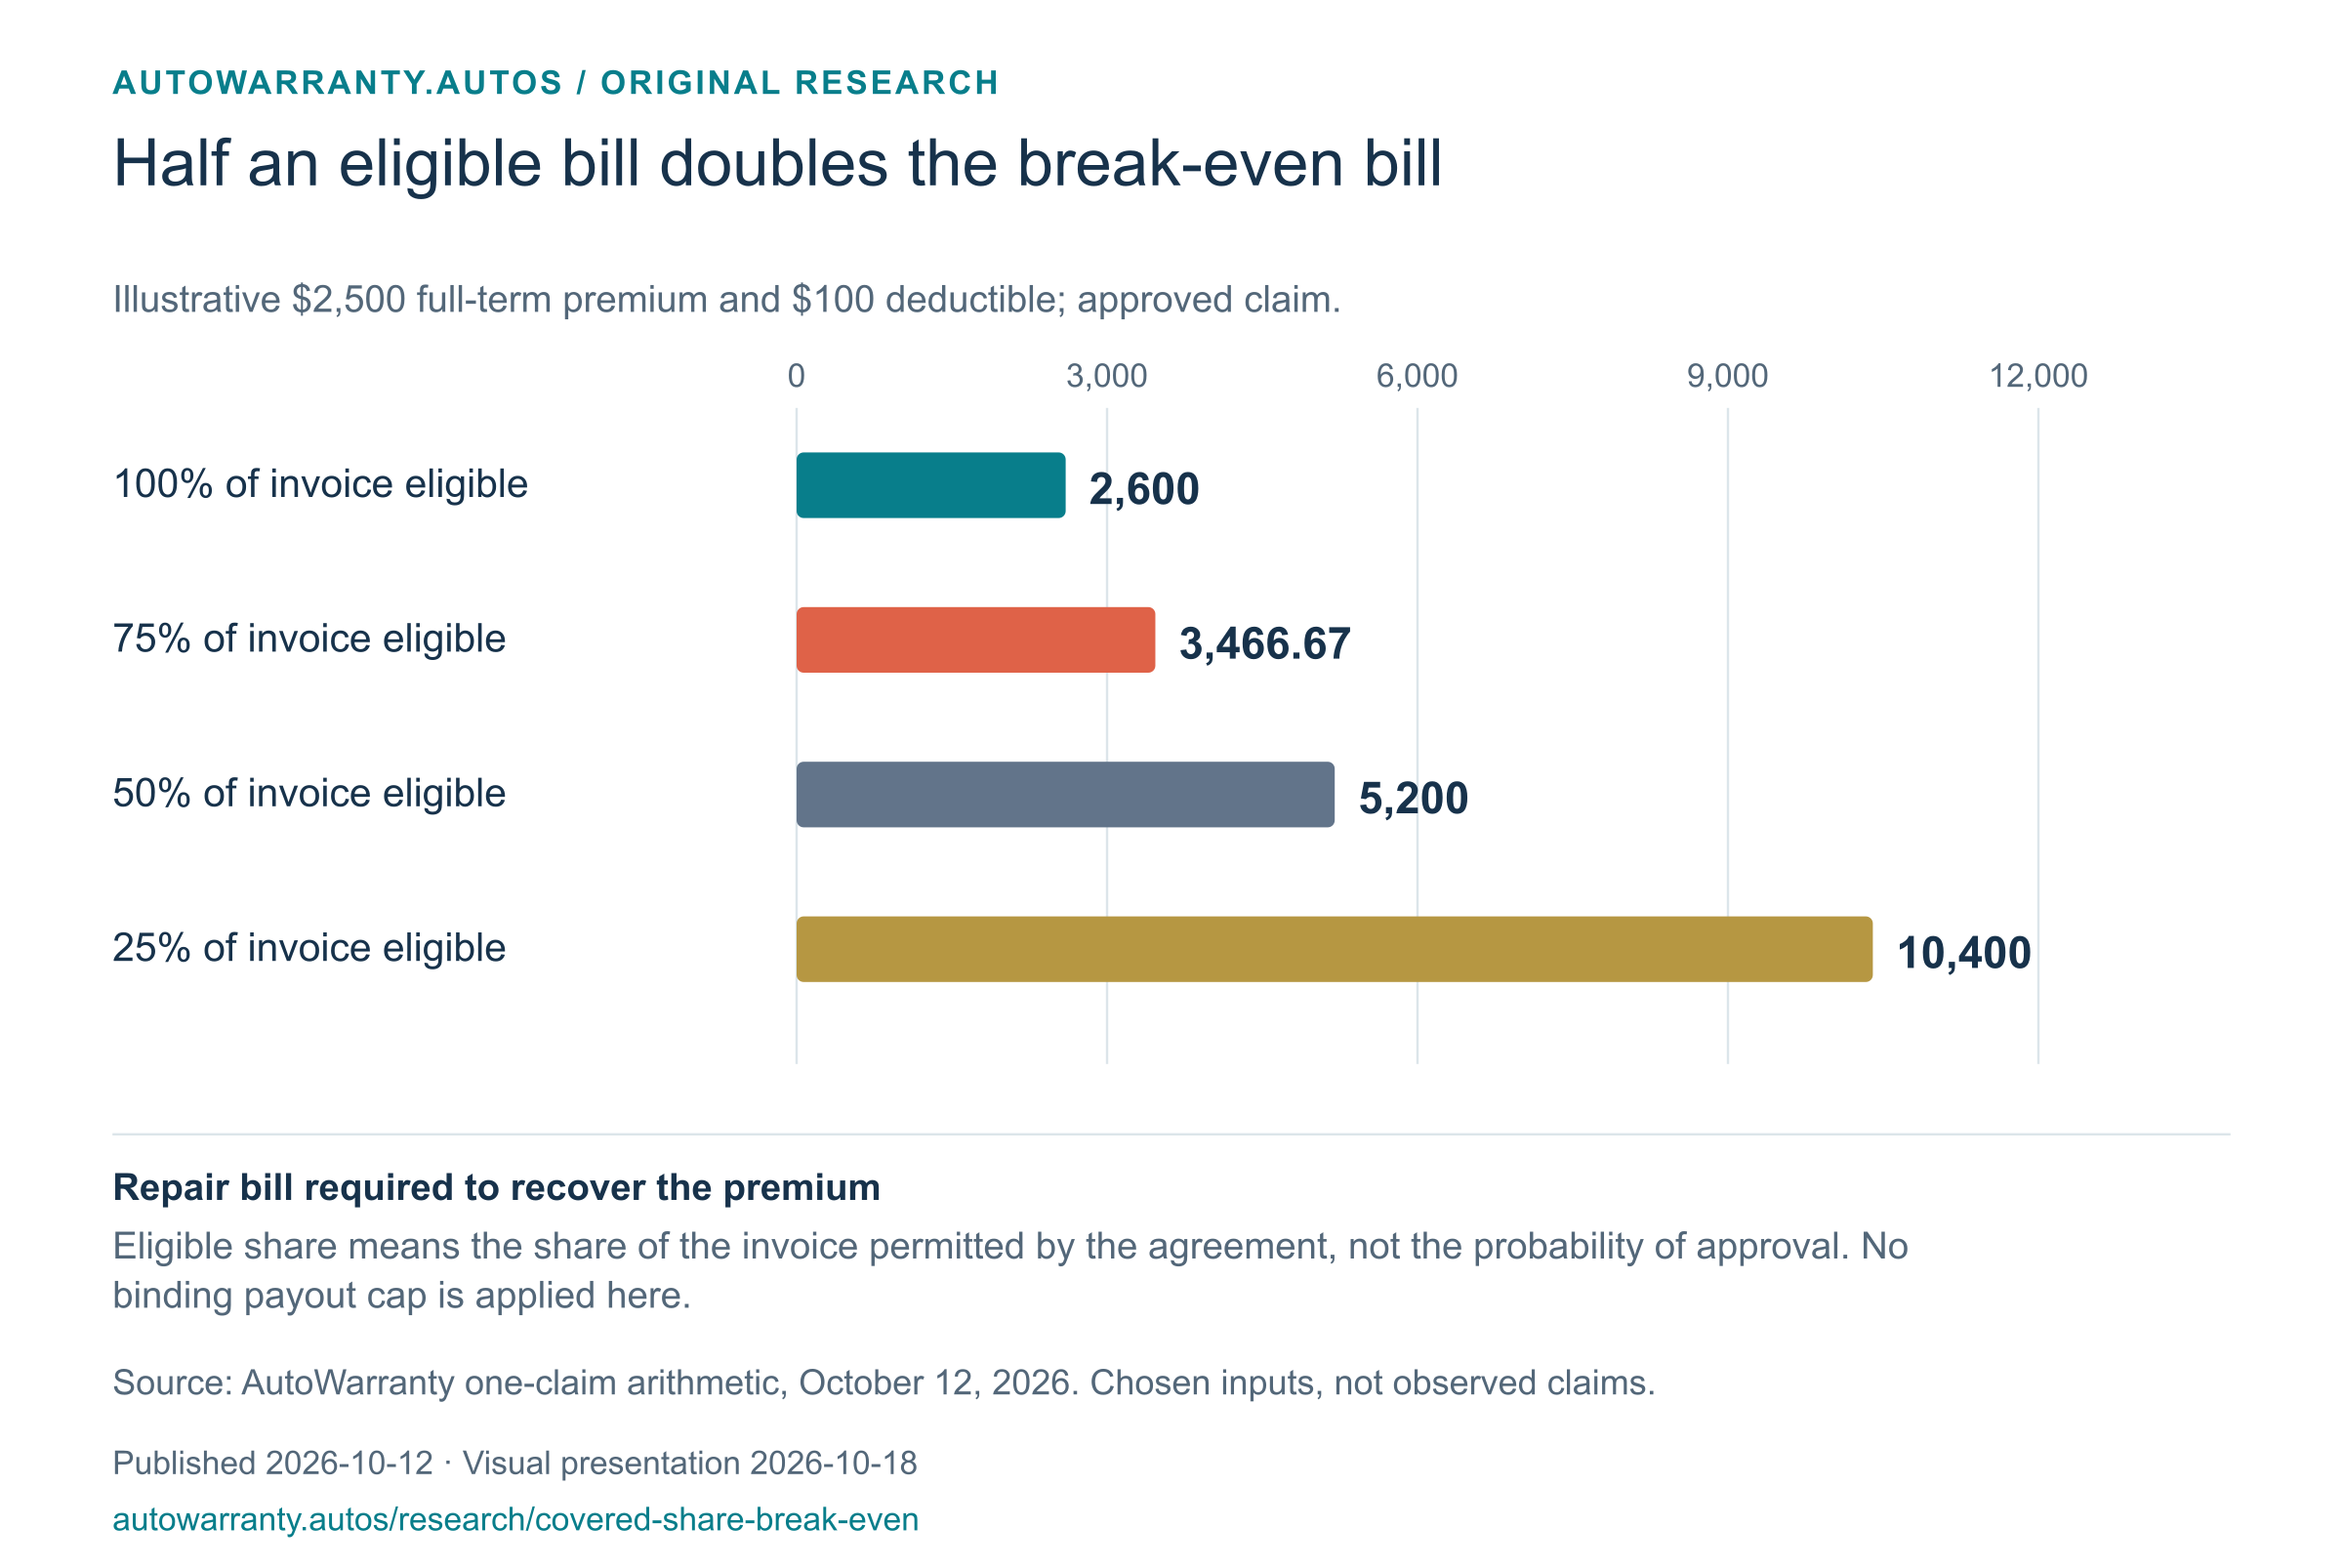
The timing of a repair still matters. A hypothetical $4,000 bill next month is difficult if the repair fund contains only $400. That is the reason to compare protection, not proof that buying a plan will save money. Use the calculator to see both sides of the budget.
Get a comparable quote, then decide
Chaiz lists Endurance, Omega, Express and ServiceContract.com, though provider presence does not mean every product or add-on is available for every car. Some provider links take you to another website for a quote. Manufacturer-backed plans discussed in our guides are separate shopping routes.
Have the year, model, mileage and state ready. Ask for the full payment schedule and current agreement, confirm the expensive components that matter to you, and keep a copy of the quoted terms. If the seller cannot explain a restriction clearly, pause the purchase.
Before you pay
- Vehicle and state qualify for the exact tier
- Full price and deductible, not only a monthly payment
- Current sample agreement and named claims administrator
- Covered parts, exclusions and total payout ceiling
- Coverage stays useful through your intended ownership
Terms and prices can change. Published examples are not personalized quotes. Hypothetical calculations are labeled; they do not predict claims or savings. Read the agreement available for your car, state and purchase date.