“Car repair insurance” is used online for several products that pay after a mechanical problem. One may be a regulated mechanical breakdown insurance policy. Another may be a vehicle service contract sold by a dealer or direct marketer. They can look similar at checkout while carrying different legal structures.
That distinction affects who oversees the product and how complaints are handled. Before comparing prices, identify what the document actually calls itself and which company owes the benefit.
Mechanical breakdown insurance versus a service contract
Mechanical breakdown insurance, often shortened to MBI, is an insurance policy for certain mechanical failures. A vehicle service contract is a separate promise to perform or pay for specified repairs. Neither replaces auto liability or collision insurance, which responds to accidents and other covered losses rather than an internal part wearing out or breaking.
State treatment varies. The California Department of Insurance explains that mechanical breakdown insurance is insurance, while vehicle service contracts are not insurance policies. California also recognizes different service-contract structures, including dealer-obligor agreements. Nevada similarly says service contracts are not insurance, although providers there must be licensed and their contracts are regulated. A product label on a search page cannot settle the legal category for every state.
Coverage language still controls the repair
Both products can use a named-component format, where only listed parts qualify. Broader coverage may work from exclusions instead. Read definitions for mechanical breakdown and covered vehicle because ordinary deterioration may not meet the trigger, even when the affected part appears elsewhere in the document.
Maintenance and collision damage are commonly outside the scope. So are pre-existing conditions. Cosmetic work usually stays with the owner, and many policies will not pay for routine replacements. If the promise sounds like it covers every trip to the mechanic, the written exclusions will probably narrow that impression quickly.
Eligibility can favor newer vehicles
Some MBI policies are offered through auto insurers and require a relatively new, low-mileage car. Service-contract companies may accept older vehicles, although the price can rise and the available coverage can narrow as mileage accumulates. Check eligibility first so you compare products you can actually buy.
Check when enrollment closes and whether renewal is guaranteed. A policy attached to an auto-insurance relationship might be renewed in shorter periods, subject to its terms. A service contract commonly sells a fixed time and mileage allowance. Compare the date and odometer at expiration, not a vague label such as “five-year coverage.”
Deductibles and claim handling shape the result
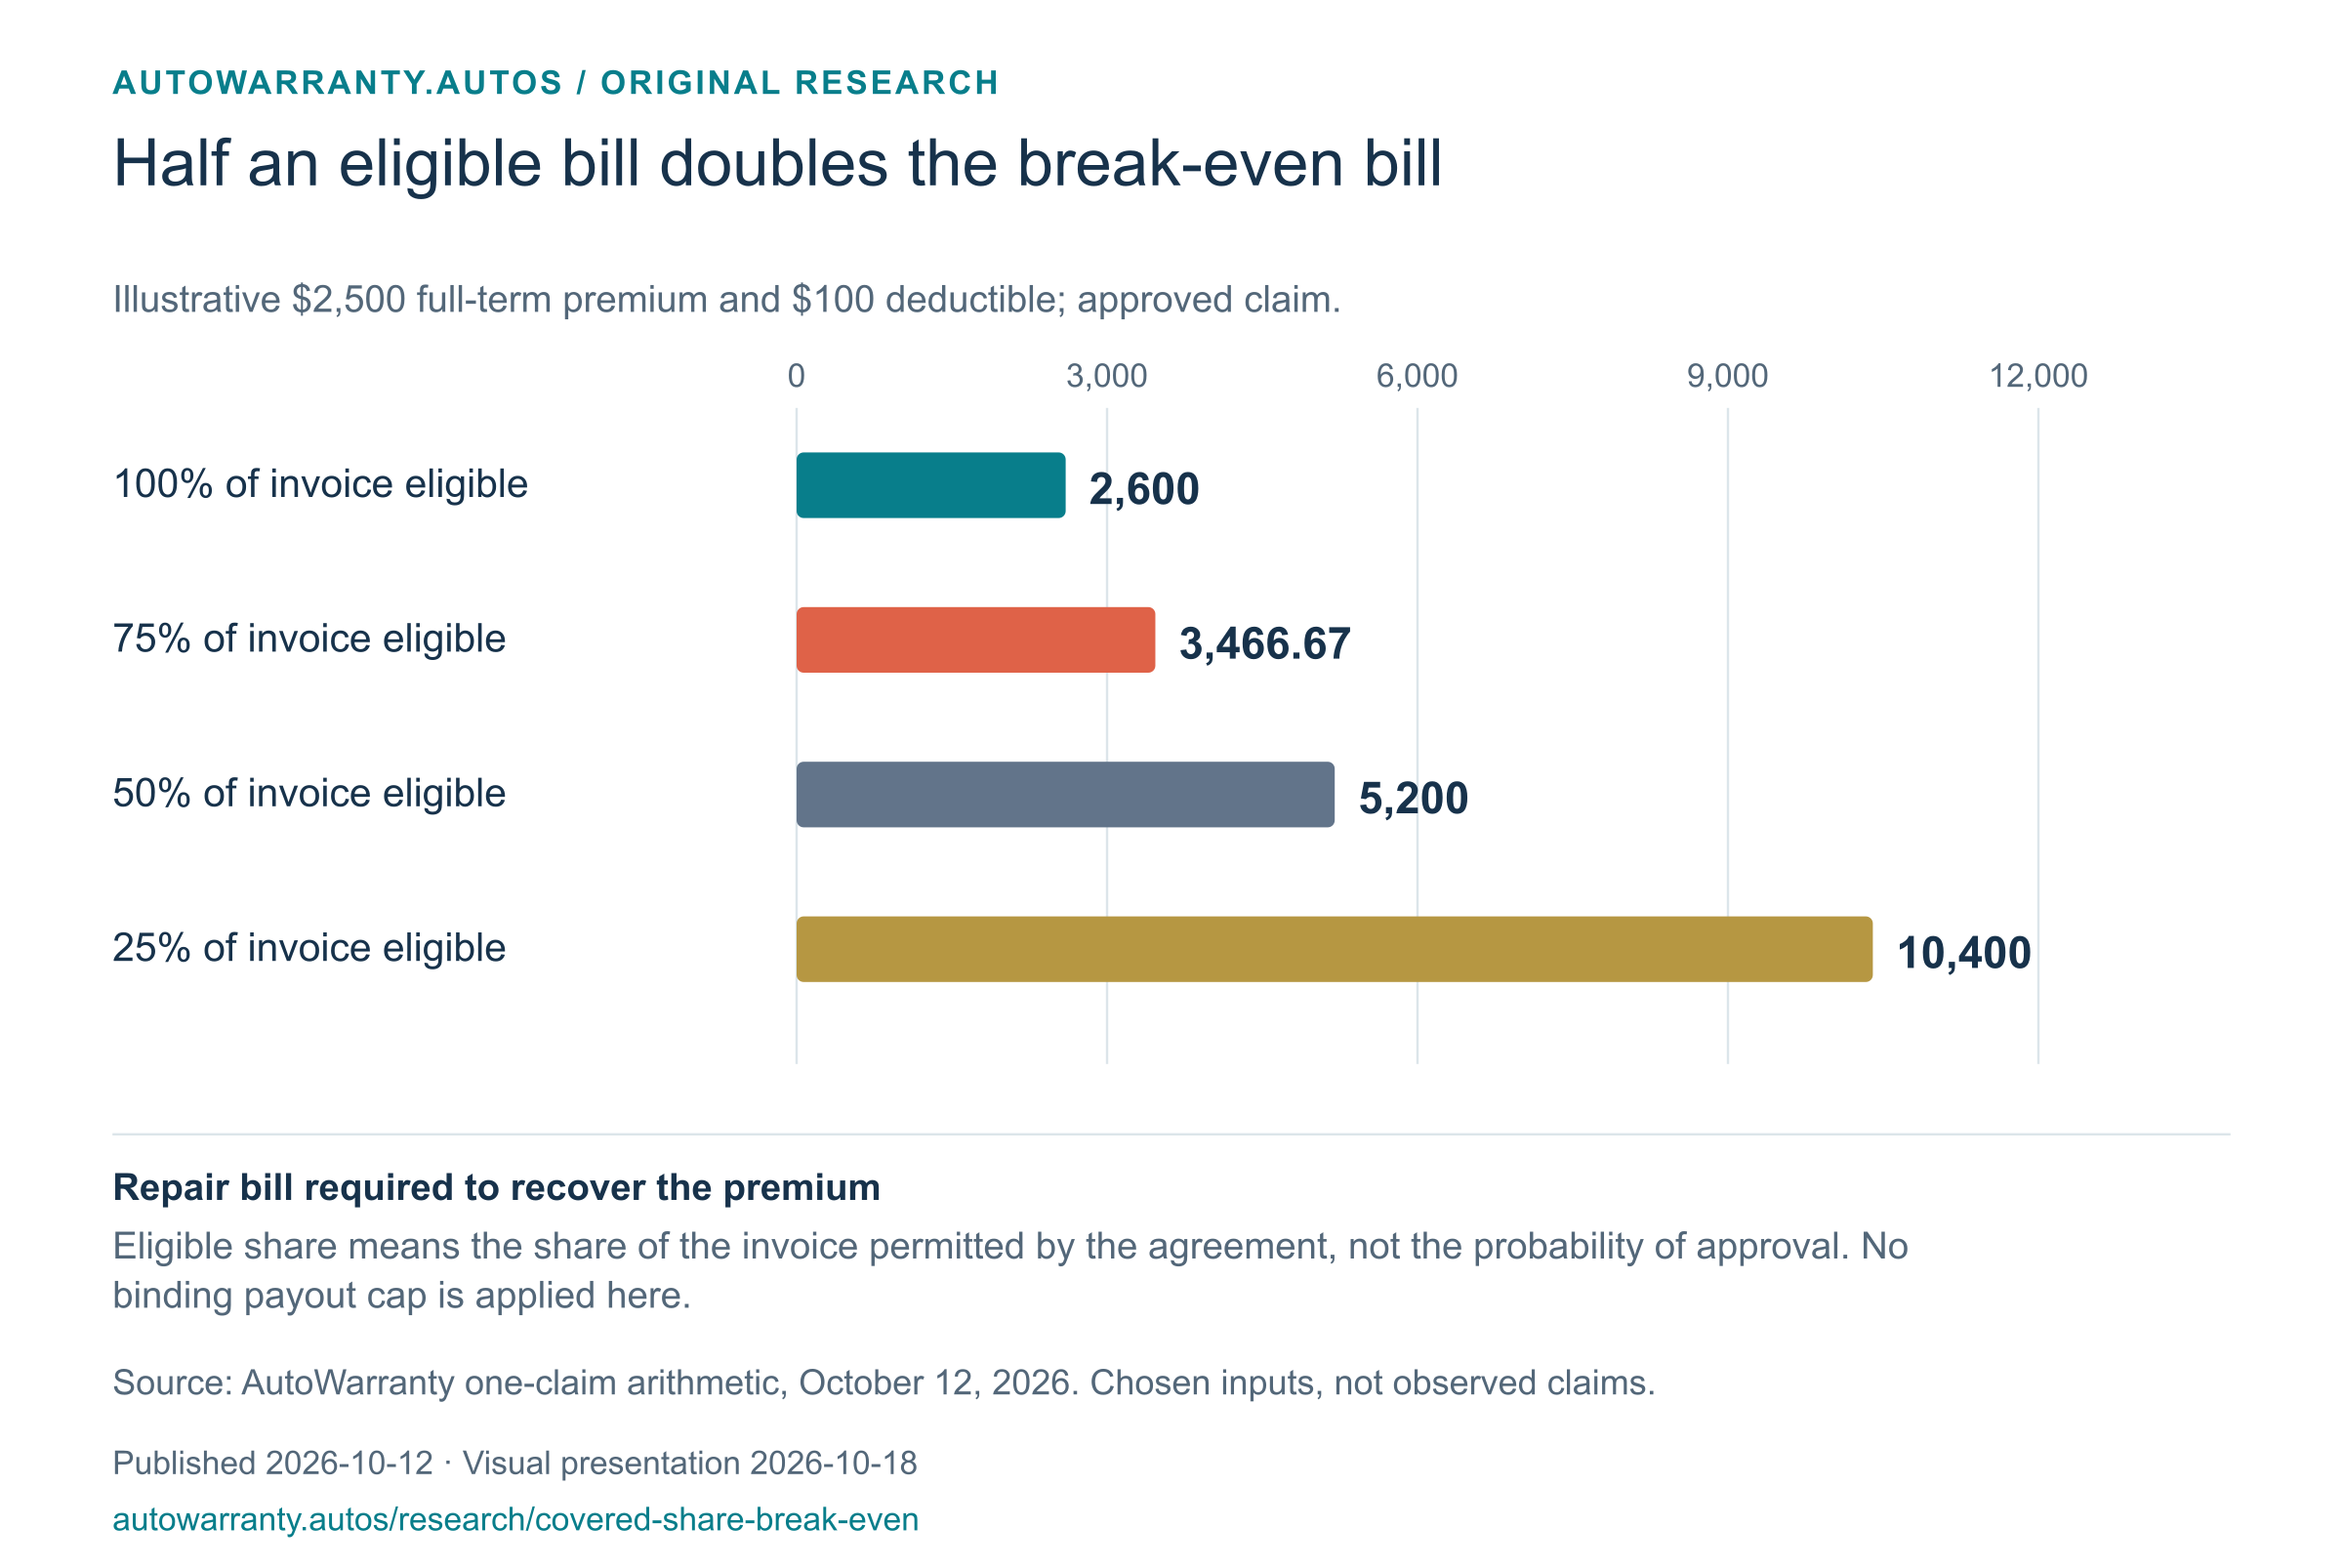
Ask whether the deductible applies per visit or per repair. A hypothetical $250 deductible equals about 4% of a covered $6,000 engine invoice. On an $800 electrical repair, it leaves you paying nearly one-third before any other exclusions.
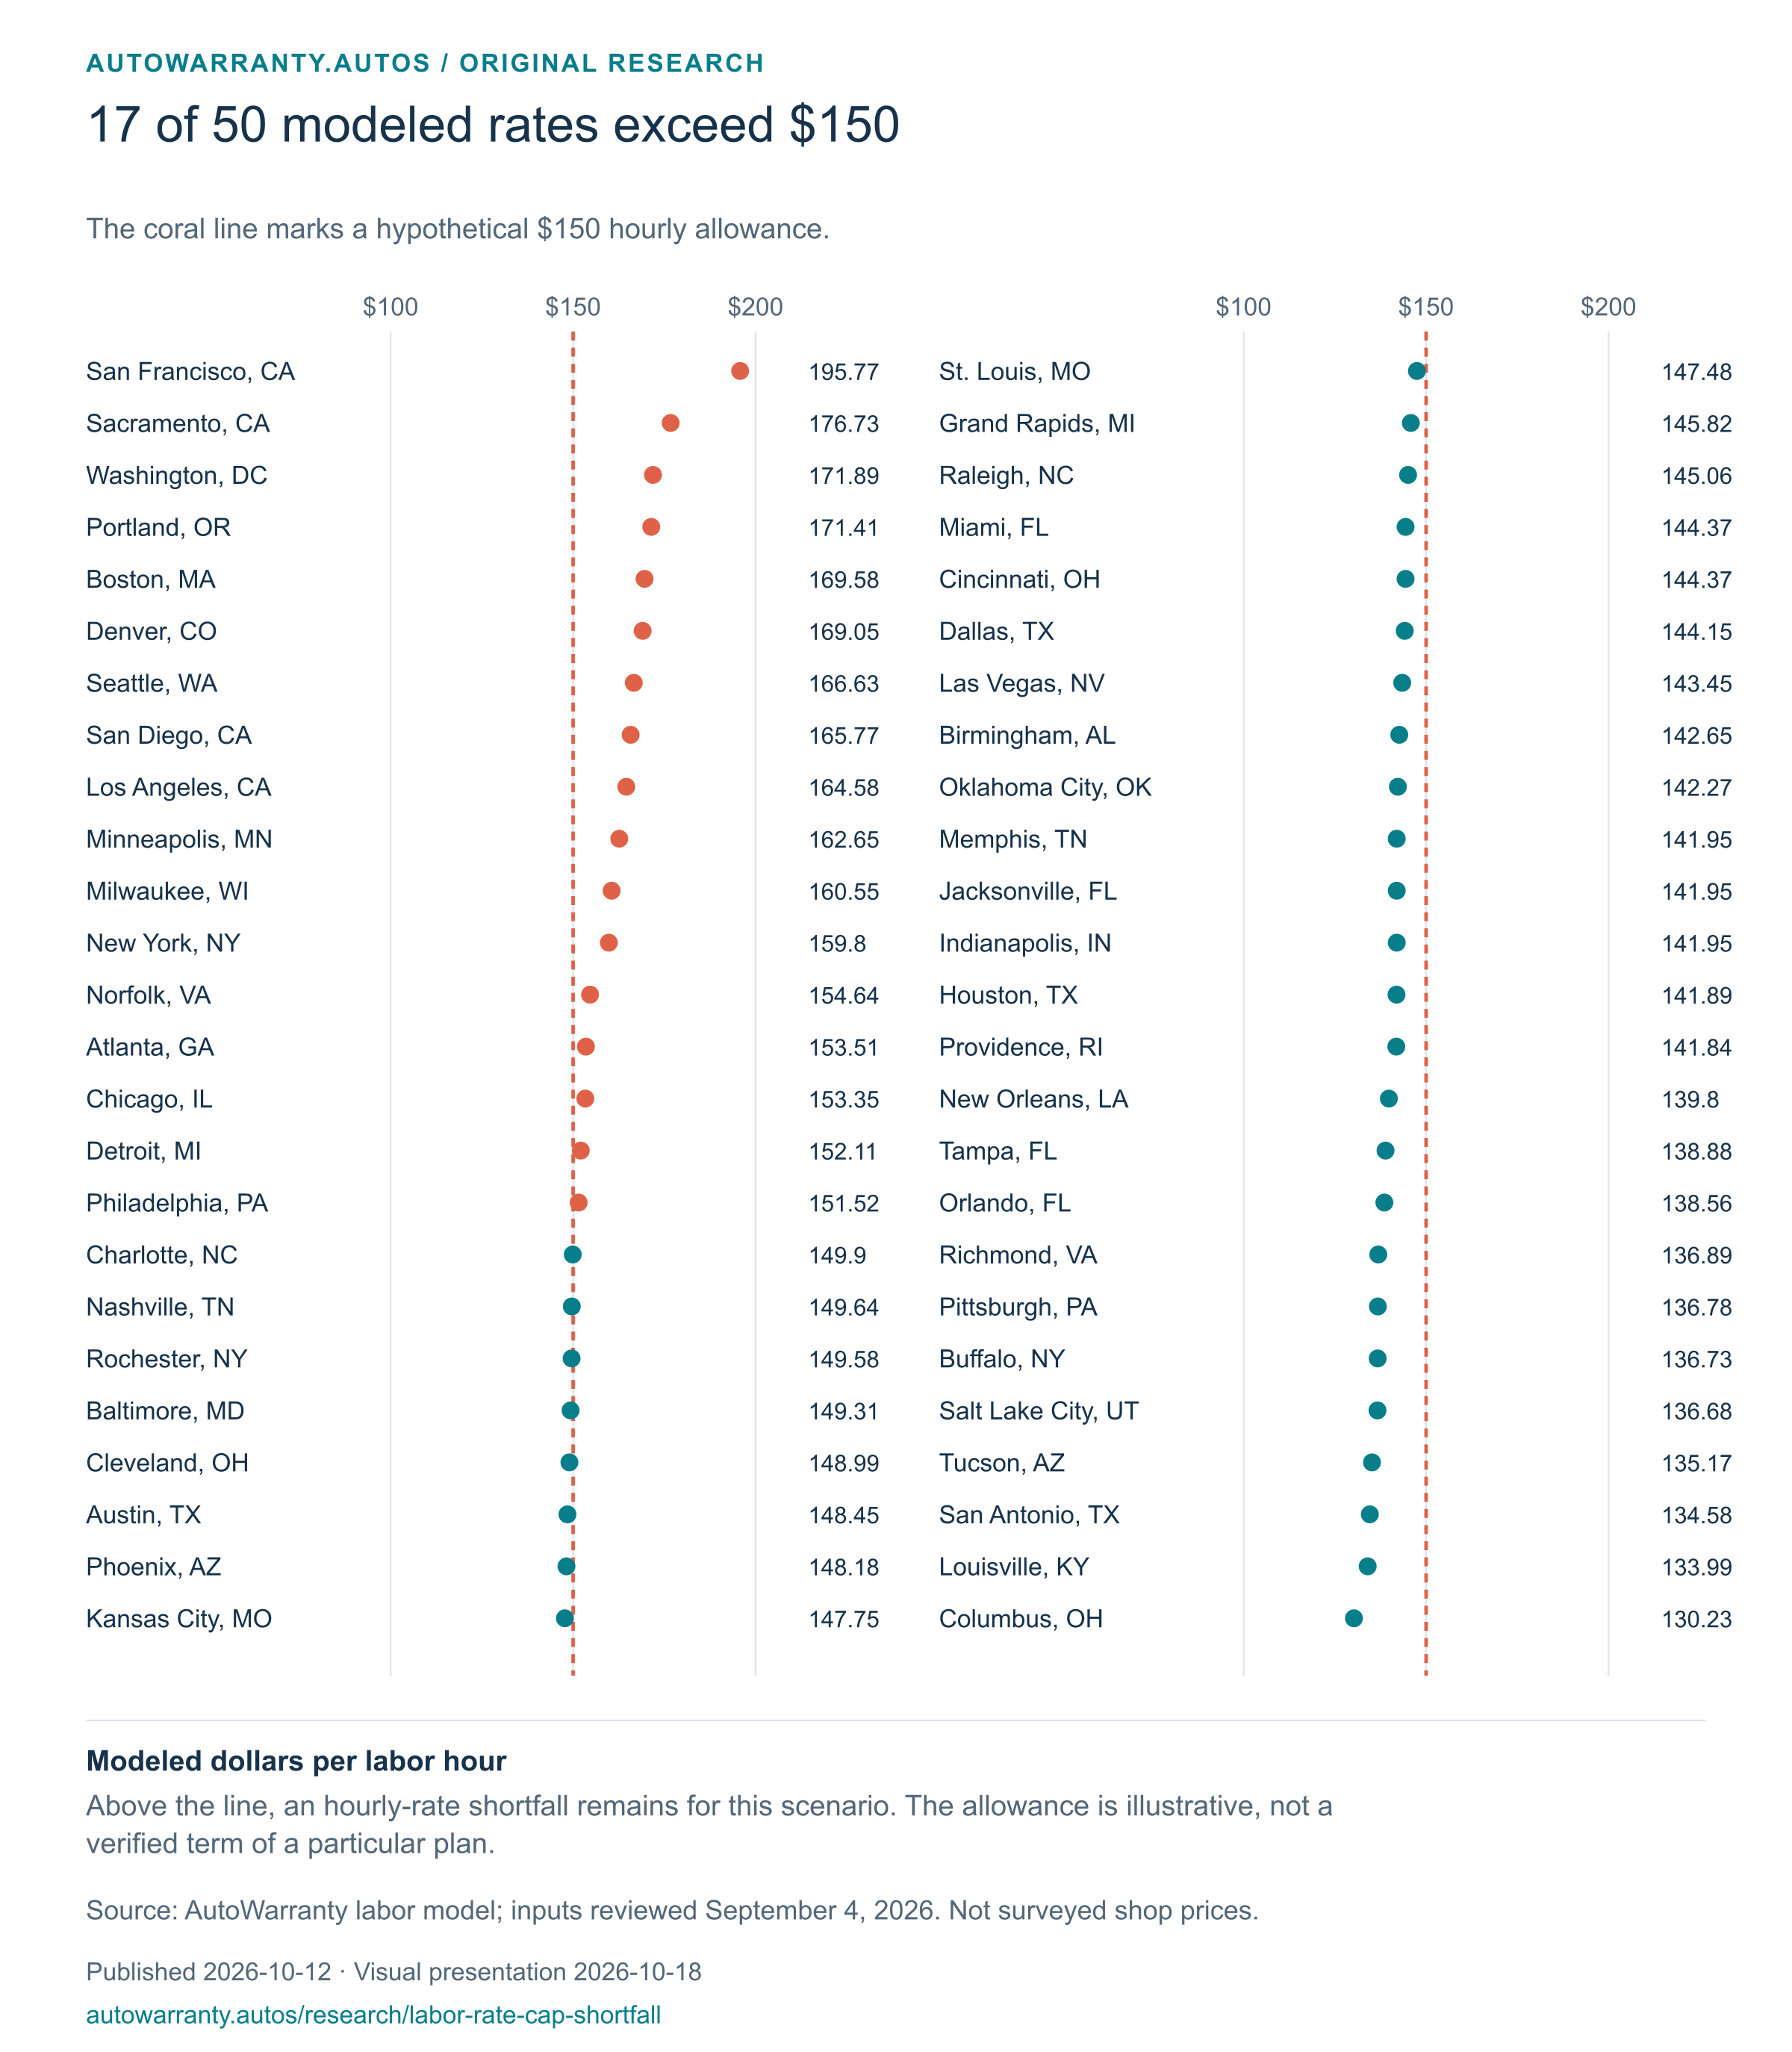
Find out whether any licensed facility may perform the work and whether preauthorization is mandatory. Confirm who pays for diagnosis or teardown when the company declines the claim. Rental reimbursement and towing are usually subject to separate limits, so neither benefit should be valued as unlimited transportation.
Compare regulation and company identity
For an insurance policy, use your state insurance department to verify the insurer and find complaint information. The National Association of Insurance Commissioners maintains links to state departments and explains that complaint indexes should be considered alongside other factors. A ratio can be useful, but it is not a substitute for reviewing coverage or financial information.
For a service contract, look for the provider or obligor named in the agreement. Your state may offer a registration lookup like Nevada’s. If the seller and administrator are separate, record both. The company answering a sales call is not necessarily the company legally responsible when a repair shop requests payment.
Decide whether predictable cost is worth the premium
Add the entire product price, financing charges and expected deductibles. Then compare that total with repairs eligible under the exact document. Do not include brake pads or other routine maintenance merely because the vehicle will probably need them.
In the Federal Reserve's 2025 survey, 30% of adults reported a major unexpected vehicle repair or replacement in the previous 12 months. Separately, 63% said they would pay a hypothetical $400 emergency expense entirely with cash, savings or a credit card paid off at the next statement. These questions measure different things; they do not show whether a service contract would save money for those respondents.
Self-funding may fit when the household can absorb a major repair and the offered coverage has low limits or wide exclusions. A well-defined product becomes more reasonable when one eligible failure would otherwise require high-interest borrowing. That is a budgeting judgment rather than a prediction that the car will break.
Before deciding whether car repair insurance is worth it, establish whether the offer is an insurance policy or a service contract. Then compare eligibility, coverage and claims rules. Rule out a low-priced plan if its repair restrictions make it impractical to use.
Primary research
Sources reviewed
- Vehicle Service Contracts and Mechanical Breakdown InsuranceCalifornia Department of Insurance
- Service ContractsNevada Division of Insurance
- State Insurance DepartmentsNational Association of Insurance Commissioners
- Economic Well-Being of U.S. Households in 2025Federal Reserve Board
Financial examples are hypothetical unless identified as published data. Coverage and contract rules vary by provider, vehicle and state.